RTD branding and packaging: how to stand out when everyone is launching a can
Where the category stands in 2026, what the can has to carry, which container fits which product, and how to get the imagery before the first run.

Ready-to-drink was the only major beverage alcohol category that grew in 2025. Every spirits, wine, and beer producer with a marketing budget has noticed, which is why the cooler door is now the most crowded shelf in the store.
That crowding changes what RTD branding has to do. The liquid is hidden inside an opaque can, the purchase happens at multipack scale, and the shopper decides in seconds.
This article covers where the category stands in 2026, what the package has to carry, which container fits which product, and how to get the imagery for all of it before the first production run.
Where the RTD market stands in 2026
RTD volumes grew 3% worldwide in 2025 while beer, wine, and spirits all declined, and the category overtook vodka in global value for the first time, according to IWSR's 2026 data release. Premium-and-above RTD volumes rose more than 15%.
The US, which accounts for about 40% of global RTD volume, tells a more specific story. Total US RTD volume slipped 1% in 2025, the category's first annual decline since 2015, but that average hides a split: malt-based RTDs fell 5% while spirits-based RTDs grew 14%, per IWSR's US Navigator data.
The Distilled Spirits Council measures the same shift in dollars. Premixed cocktails, including spirits-based RTDs, reached $3.8 billion in US supplier revenue in 2025, up 16.4%, while every other major spirits category declined, according to the DISCUS Annual Economic Briefing of February 2026.
Read together, the numbers say one thing. Growth has moved from anything in a can to spirits-based, higher-priced, clearly branded products, and the launches competing for that growth are more numerous than ever.

What RTD branding has to do that wine branding does not
An RTD package carries more of the selling job than a wine or spirits bottle does, for three structural reasons.
The liquid is invisible
Most RTDs ship in aluminum, so the color and clarity that sell a rosé or a gin are hidden. The can has to communicate flavor, base spirit, and ABV on its surface alone.
That is why category-leading designs put the flavor cue and the spirit name at eye level, with the brand mark second.
Two designs, one product
A single can has to work on its own in a hand and as a repeated pattern of four, six, or twelve inside a carton. Designs that look complete as a single unit often turn into visual noise in a multipack, and the reverse is also true.
Both views need to be judged before anything is printed.
The category has no fixed vocabulary
Wine has centuries of label convention to lean on. RTD borrows freely from beer, cocktails, soda, and wellness drinks, so a brand has to choose its visual reference point deliberately.
A pre-mixed Negroni in a glass bottle and a tequila soda in a 355 ml can are solving different problems, and their packaging should not look like siblings. IWSR's consulting team makes the same point about the category as a whole: a launch now needs a defined role in the drinker's repertoire, not just a can, a flavor, and distribution.

The RTD segments driving the category
Spirits-based canned cocktails
This is where the growth is. Classic serves lead the launches: margarita, paloma, espresso martini, Negroni, Old Fashioned, and vodka soda, usually at a higher ABV and a higher price than the seltzer generation.
The packaging pattern follows the base spirit. Named spirit brands on the front panel, smaller cans for higher-ABV serves, and glass bottles for products positioned as a bar-quality cocktail rather than a refresher.
Hard seltzers and flavored malt beverages
Malt-based RTD volume fell 5% in the US in 2025, and DISCUS reports malt-based seltzers lost 14 points of share while spirits-based RTDs gained 11. The segment is not gone, but a seltzer launch in 2026 competes on price and flavor range rather than novelty.
Wine spritzers and wine cocktails
Wine-based RTDs span slim cans, single-serve aluminum bottles, and full 750 ml bottles of pre-mixed sangria. The branding problem here is consistency: many wine cocktail brands present differently in every format, which weakens recognition when the can and the bottle sit in different aisles.


No-alcohol and low-alcohol RTDs
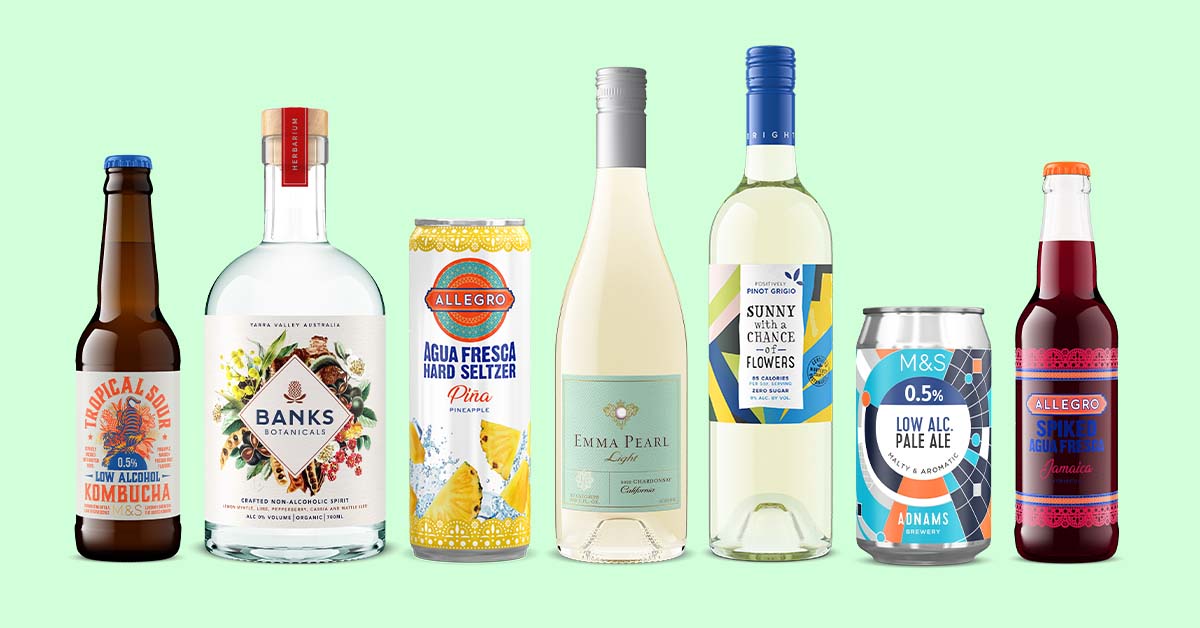
No-alcohol beer volume grew 15% in the US in 2025, per IWSR, and non-alcoholic cocktails in RTD format ride the same demand. These products use the design language of their alcoholic counterparts on purpose, so the shopper reads them as a cocktail first and a no-alcohol choice second.

Flavored beer crossing into RTD territory
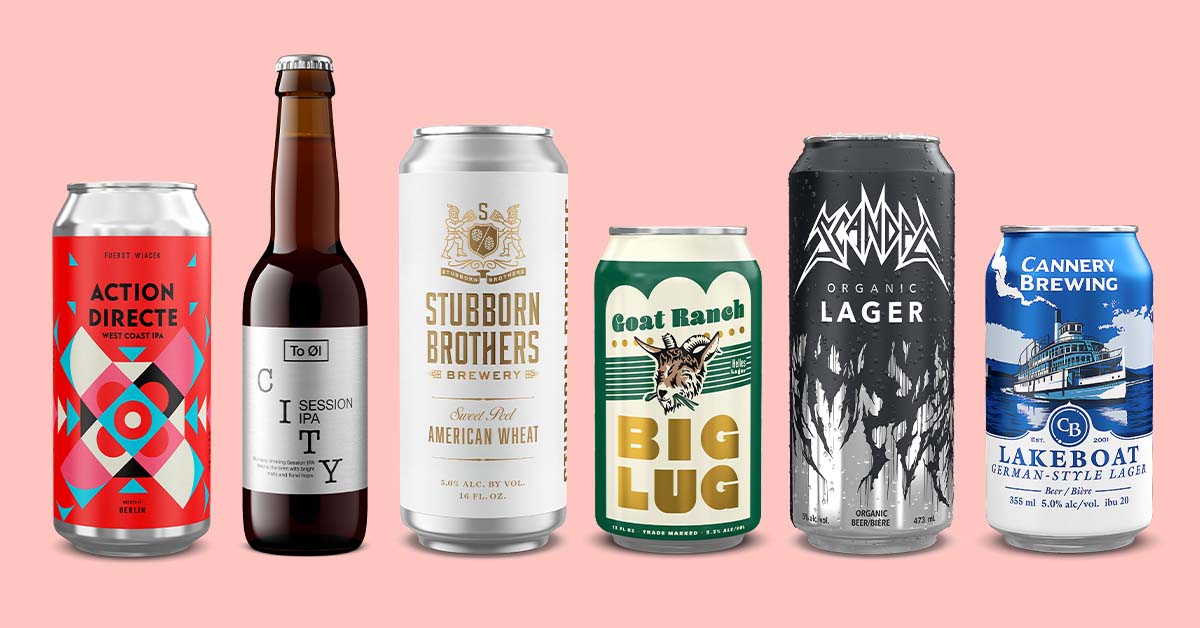
Fruited sours and flavored lagers are packaged like RTDs: bright illustration, flavor first, brewery second. For a brewery this is the lowest-cost route into the category, because the canning line and the distributor already exist.

Choosing the RTD container
The container decides portion size, carbonation life, shelf life, and how much of the surface the brand controls. Four formats cover nearly every RTD on the market.
- Aluminum cans: Cans block light entirely, hold carbonation well, ship light, and give a 360-degree print surface. They are also the most recycled drinks package in the US: 43% of cans shipped in 2023 were recycled, against 39.6% for glass and 20% for PET, and the average US can is 71% recycled content, per the Aluminum Association and Can Manufacturers Institute. Common sizes run from 187 ml slim cans through 250 ml, 355 ml, and 473 ml.
- Glass bottles: The premium signal. Glass shows the liquid, takes embossing, foil, and heavier label stocks, and is the natural format for a pre-mixed cocktail sold at spirits prices, including 375 ml and 750 ml sharing formats. It costs more to ship, and many outdoor venues do not allow it.
- PET and plastic bottles: Light, shatter-resistant, and inexpensive, so common for tea, coffee, and mixer RTDs. The trade-off is perceived quality and a weaker sustainability story.
- Cartons: Aseptic cartons protect non-carbonated, ingredient-rich drinks from heat and light for ambient shelf life. They are common in juice-based and wellness RTDs and rare in alcohol.
Whatever the primary container, plan the secondary packaging at the same time. The multipack is where the shopper meets the brand, and the carton is where the brand story has room to be told.


Container and format settled, the design work starts. The launches that kept their shelf space through the seltzer shakeout share a few traits.
Design directions that hold up in 2026
- Flavor and base spirit first: "Tequila soda with lime" at the top of the can, brand name second. The shopper is buying a serve before buying a house.
- One idea per surface: Simple, high-contrast layouts read at cooler-door distance. Detail belongs on the carton, not the can.
- Borrowing done on purpose: Craft-beer illustration, wine typography, or cocktail-bar restraint, chosen to match the occasion the product is built for.
- Premium cues that survive the format: Matte finishes, embossed cans, and glass for the top tier, because premium-and-above RTDs grew more than 15% in 2025 while the middle shrank.
- Specific sustainability claims: A stated material and recycled-content figure gives the shopper something to check. A leaf icon gives them nothing.
- Consistency across formats: If the same cocktail ships in a can and a bottle, the two should be recognizable as one brand from across the store.

Getting RTD product imagery before the first run
Most of the decisions above get made before a single can is filled. The distributor sell sheet, the retailer listing, the pre-order page, and the carton artwork all need a finished-looking product image while the product is still a label file.
That is the problem Outshinery Studio is built for. A trained 3D artist builds a photorealistic Product Shot from your can or label artwork and the container specification, so the can, the bottle, and the multipack exist as images before they exist as objects. No sample in the mail, no photoshoot, no reshoot when the ABV line changes.
Studio covers the formats RTD needs: standard and slim aluminum cans, custom glass bottles built from the manufacturer's technical drawing, 4-pack and 12-pack cartons, and lifestyle scenes, videos, and POS displays rendered from the same 3D model. ABV and liquid color updates on an existing Product Shot are free, and a new flavor in the same can is a new label file on a model that already exists, not a new shoot. The RTD and cider product photography page shows the range.
One boundary worth stating plainly. Outshinery Lite, the self-serve bottle shot generator, renders glass-bottle RTDs with a flat label in its beer and cider bottle shapes at $29 per image, and it does not do cans. Anything canned, embossed, or in a custom bottle is Studio work.
Frequently asked questions
How is RTD packaging different from wine or beer packaging?
RTD packaging has to sell a hidden liquid, usually inside an aluminum can, and it has to work twice: as a single unit in the hand and as a repeated pattern inside a 4-, 6-, or 12-pack. Flavor and base spirit typically lead the design with the brand name second, because shoppers buy the serve before they buy the house.
Which container is best for a ready-to-drink cocktail?
Aluminum cans suit carbonated, single-serve cocktails; they block light, hold carbonation, and are the most recycled drinks package in the US. Glass bottles suit higher-ABV, premium-priced cocktails and sharing formats of 375 ml or more. The choice follows the price tier and the occasion, not the other way around.
Are spirits-based or malt-based RTDs growing faster?
Spirits-based. In the US in 2025, spirits-based RTD volume grew 14% while malt-based RTD volume fell 5%, according to IWSR, and DISCUS reports premixed spirits cocktails reached $3.8 billion in supplier revenue, up 16.4%.
How do RTD brands get product images before the cans exist?
Through photorealistic 3D rendering. Outshinery Studio builds a Product Shot from the can or label artwork and the container specification, so distributor sell sheets, retailer listings, and multipack designs can be finished before the first production run. Turnaround is days, without a photoshoot or a physical sample.
Does Outshinery Lite make can images?
No. Lite renders glass-bottle products with a flat label in its wine, cider, and beer bottle shapes, which covers bottled RTDs but not cans. Canned RTDs, embossed bottles, and custom container shapes go through Outshinery Studio.

Keep reading
For the packaging fundamentals that carry across every beverage category, read how to position your packaging for sales success. And for the closest format neighbor, another single-serve can sold in multipacks and facing the same opaque-surface design problem, see where canned wine is heading.
The RTD launch packaging checklist
- Role: One occasion and one serve the product owns, written down before design starts
- Container: Exact can size and end type, or the glass manufacturer's drawing and mold number
- Front panel: Flavor and base spirit readable at cooler-door distance, brand second, ABV where regulation requires it
- Multipack test: The single-unit design reviewed as a 4-pack and 12-pack pattern before print approval
- Print finishes: Matte varnish, embossing, or metallic ink called out to the printer and to the 3D artist
- Sustainability claim: Material and recycled-content figure stated, no unsourced icons
- Imagery: Product Shots of can, bottle, and carton ordered from artwork, ahead of the first run
Settling these seven before the print run is the difference between a launch and a relabel.